Free infectious disease disinfection tool
Infectious Disease Disinfection Insurance Claim Organizer
A guided checklist from finding the policy to tracking the insurer’s decision, with a printable summary of where the claim stands.
Who pays for outbreak disinfection depends on your policy wording, your lease, and the type of facility. It may be a covered loss, a normal operating cost, or something a landlord must fund. Some businesses carry add-on coverage for contamination or contagious disease. Many find the work comes out of their own budget. This organizer walks you through steps that apply either way. You find the policy and any add-ons that matter. You describe the cause of loss in the insurer's terms and give notice. You record the outbreak and the response, get a written work plan, and track the insurer's decision. Each step has a checklist. Your progress is saved in your browser. The result is a summary you can print for an insurer, a landlord, or your leaders.
The organizer does not predict whether a claim will be paid, and no vendor can either. Its value is in building a file that tells a clear, steady story. It shows when the cluster was found, who was told, which spaces were treated, what products were used, and what the facility paid. That file helps with more than insurance. Schools use it to answer district and parent questions. Clinics and group homes use it for licensing inspections. Office tenants use it when they talk with landlords about who pays for common areas. Buildings with several tenants should record which spaces are shared and which belong to one tenant. Leases often split who pays along that line. Keep the organizer with your incident log.
How to use it
- 1Find the policy. Note any add-ons for contamination, contagious disease, or business interruption.
- 2Complete each step in order. Check off items as you gather documents and make calls.
- 3Record dates, names, claim numbers, and decisions in the notes fields as they happen.
- 4Print the summary when the insurer decides. File it with the vendor's report and your incident log.
Prefer to ask a person?
Your request is sent to the follow-up inbox. A coordinator can reply by email. Not for emergencies; call 911 first if anyone is in danger.
Organize an insurance claim
Infectious Disease Disinfection insurance claim organizer
A checklist to keep the claim orderly. It stores nothing on our servers; copy the summary to your own notes.
0 of 18 steps recorded (0%)
Print or paste the summary into your own records. Coverage is the carrier's decision under the policy; keep every answer in writing.
A worked example
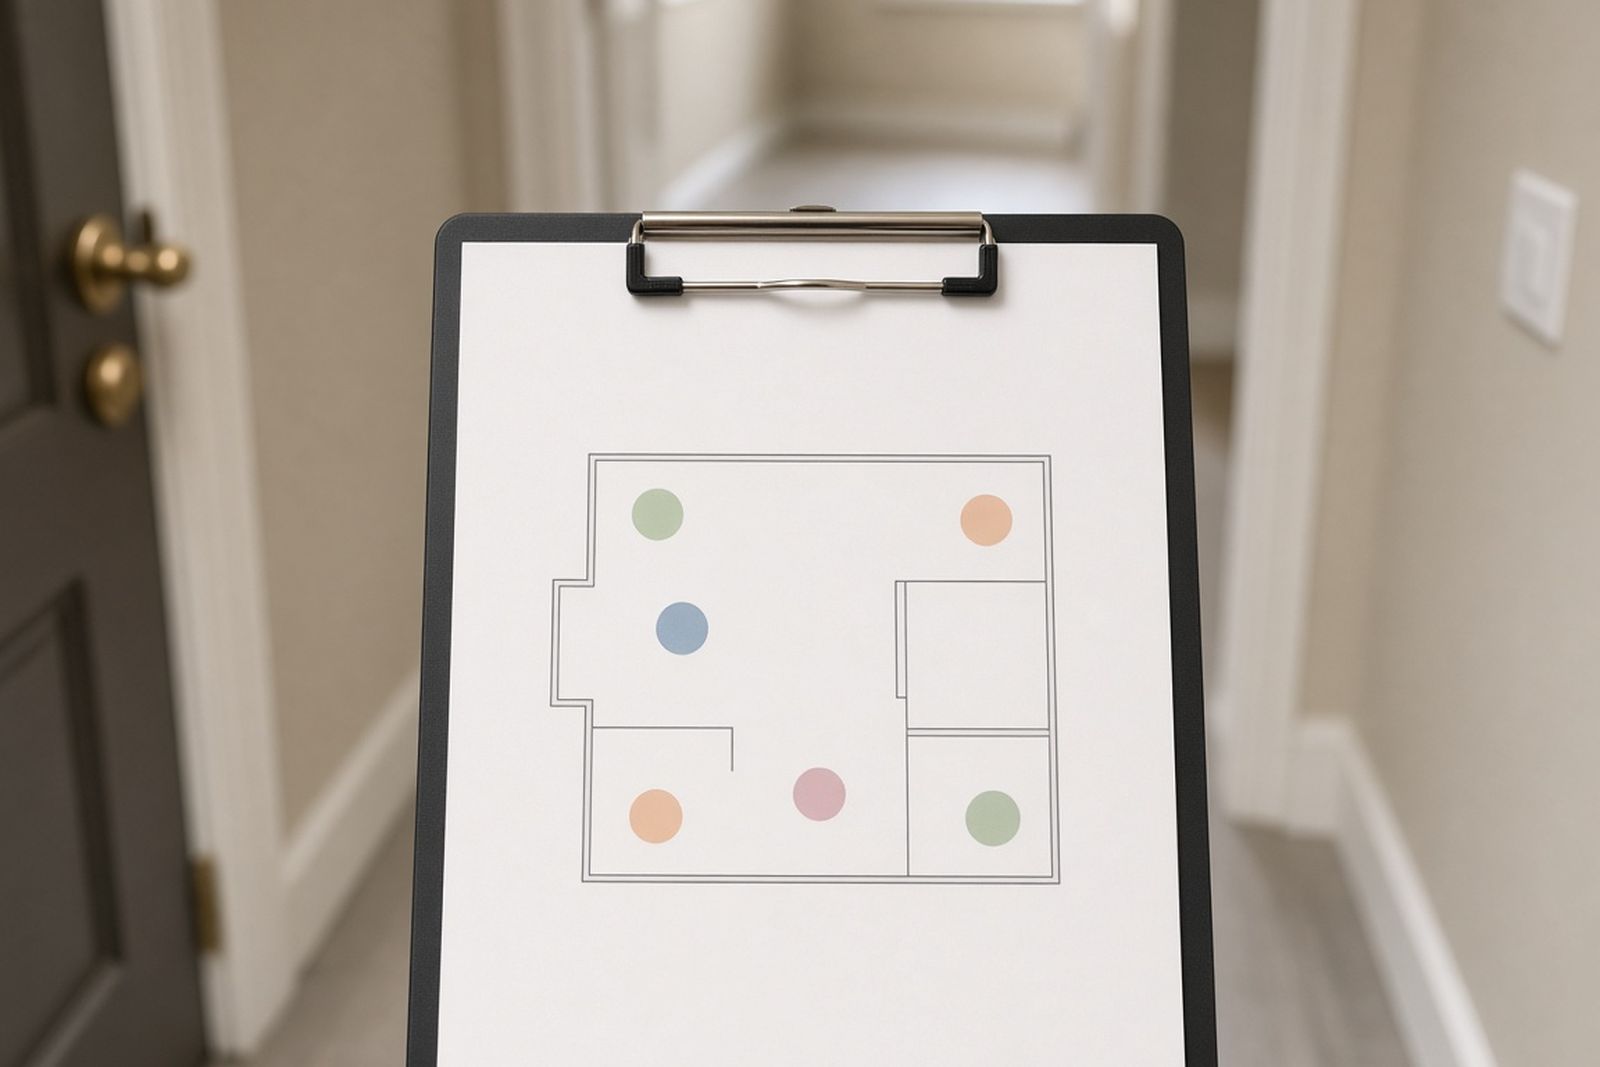
Picture a made-up dental clinic. It learns that a staff member worked several days while sick and contagious with a respiratory illness. The owners ask the practice manager to find out if their policy will help pay for a professional disinfection. She opens the organizer. The first step sends her to the policy. There she finds an add-on for contagious disease with specific wording about what triggers it. She records the cause of loss in those terms. She notes the date the cluster was found and the dates of exposure. She gives notice to the insurer and logs the claim number and contact. The records step prompts her to gather the staff attendance record and the notice sent to patients. She also gathers the vendor's high-touch map of the treatment rooms and waiting area. She adds the final report with product registration numbers and contact times. When the insurer asks for the work plan, she attaches it and notes the date of the request. In the end, the insurer covers part of the cost. It explains which costs fell outside the add-on. She records that decision and the reasons. The printed summary goes to the owners. A copy is filed with the infection control records the practice keeps for its state board.
Facts worth knowing
HomeAdvisor says disinfecting a home costs from $15 to $400 or more, depending on whether you do it yourself or hire a professional.
Why it matters: The range is wide, so ask for a written quote, and expect specialized biohazard work to cost you more.
A cleaning trade group's December 2025 price guide lists electrostatic disinfection at $0.10 to $0.30 per square foot for commercial buildings.
Why it matters: Use this as a rough range to compare quotes; your price may differ by region, size and how often you need service.
OSHA requires employers whose workers may contact blood to keep a written safety plan, offer hepatitis B shots within 10 working days, and train workers at least yearly.
Why it matters: When you hire a cleanup company, you can ask whether its workers have this training and a written plan.
Insurance Claim Organizer questions for infectious disease disinfection
What is the cause of loss for an outbreak?
Insurers want a specific triggering event, described in the policy's own words. That might be a confirmed case on the premises or a public health order. It might be a contamination event, such as someone vomiting in a common area. Record what really happened, with dates. Let the policy wording decide whether it fits. Do not describe the event as something it was not.
Should I wait for the carrier's approval before hiring a vendor?
Usually you cannot, because the facility needs to respond quickly. Tell the insurer early, write everything down, and ask what they need to see. Go ahead with the work on your own authority and keep the file complete. If coverage is denied, the same records support the expense with your leaders or a landlord.
Who pays in a multi-tenant office building?
It depends on the lease and where the outbreak concern is. Spaces used by one tenant are often that tenant's job. Shared lobbies, elevators, and restrooms often fall to the landlord. Record which spaces were treated and who asked for the work. Keep emails and letters with property management in the organizer's notes. Disputes usually turn on that record.
Does business interruption coverage apply when an outbreak closes us?
Sometimes. It depends on the policy wording, which has been heavily disputed in recent years. Read the policy and ask your broker. Record any closure dates and lost activity in the notes. The organizer helps you lay out the facts. Whether they trigger coverage is up to the insurer. If needed, it is also a question for your state insurance regulator.
Can a school or nonprofit use this organizer?
Yes. Districts and nonprofits usually have property and liability policies through a pool or an insurer, and the steps are the same. Even where no claim is possible, the organizer builds the expense and records file. Boards, auditors, and grant programs often ask for that file. Change the step labels to fit your group's language as needed.
What if we are not sure whether any policy applies?
Build the file anyway. As the response unfolds, record dates, affected areas, vendor scopes, invoices, and any public health instructions. Then ask your broker or risk pool to review the policy wording before you decide whether to notify an insurer. A tidy file costs little to create. It is far harder to rebuild weeks later if coverage turns out to be possible.
How should we separate costs for the outbreak from normal cleaning costs?
Keep outbreak invoices, overtime hours, supplies bought just for the response, and thrown-out items in their own section. Use dates that match the outbreak period. Note what your routine cleaning normally costs. Then an adjuster or finance office can see the difference. If you mix routine and outbreak costs on the same line, it is hard for anyone to judge what the event really cost.
Related community polls
Vote to see how other people answered. You can change your answer at any time.
When your facility had an illness cluster, how did you handle cleaning?
How did you decide whether to close all or part of the facility?
Other infectious disease disinfection tools
Cost Range Estimator
Set the affected area, surface types, severity and extras to see a rough cost range and what pushes it up or down.
OpenCompany Vetting Checklist
Fifteen questions to ask any cleanup company, a score that shows how ready you are to hire, and a list of what is still unanswered.
OpenFirst 24 Hours Planner
Tell the planner a few facts about the situation and get an ordered list of who to call, what not to touch, and what to photograph.
OpenWaste & Disposal Classifier
Five questions about the material point to the likely waste category and which authority to confirm the rules with.
OpenDIY or Call a Pro? Risk Check
Eight yes-or-no questions that produce a risk level and explain when professional help is the safer choice.
OpenMore on infectious disease disinfection
Infectious Disease Disinfection services
Learn how expert outbreak disinfection works in schools, offices, clinics, gyms, and care homes. See each step, from mapping high-touch spots to checking contact times and records.
Costs explained
What drives the price, published cost ranges, and how to read a written quote line by line.
Insurance and payment
Which policies may respond, how to document a claim, and what to do if coverage is denied.
Community polls
See how other facility managers handled closing, vendors, and telling people during outbreaks. Then take the questions that come up to your own team.
Knowledge quiz
Test what you know about product labels, contact times, keeping germs contained, and records. Do it before you approve a disinfection plan or brief your leaders.
Articles and resources
Articles on norovirus in schools, MRSA in gyms, EPA List N, contact times, and notes to parents. They are written for the people in charge of a building.
City guides
Find disinfection companies who serve your area for facility outbreaks. Learn what to confirm about products, training, and records before you hire.