Short answer
Coverage for meth lab cleanup is uncertain. It depends heavily on the type of policy you hold. Many homeowners and landlord policies have pollution, contamination or intentional-act wording that insurers may apply to drug residue. Some landlord policies or add-ons deal with tenant damage more directly. Test first, report promptly and ask your insurer for its position in writing before you approve large removal work.
Why meth contamination is a hard insurance question
Meth residue is a chemical problem, not a fire or a flood. It settles unseen on walls, ceilings, ductwork and soft materials. It may only come to light when a tenant leaves, a buyer orders testing or law enforcement reports a seizure.
Insurers read that kind of loss through several parts of a policy at once. Pollution or contamination wording can come into play. So can exclusions for intentional or criminal acts and conditions about who lives in the property. The same facts might lead one insurer to deny and another to pay part. It depends on the exact policy form and its endorsements, the add-ons that change it.
That is why your most useful first step is not guessing. Get the policy. Read the exclusions section with your agent. Then ask the insurer to name the wording it is weighing.
Your own home vs a rental: does it matter?
It matters a great deal. A homeowners policy for an owner-occupied home is written for a household living in the property. A landlord or dwelling fire policy is written for a property rented to others. Some of these policies, or endorsements added to them, speak more directly to damage caused by tenants.
If you are a landlord, check whether your policy includes any coverage for malicious damage or tenant vandalism. Read how it defines those terms. Some insurers may treat contamination from making the drug differently from contamination caused by smoking. Some may exclude both. Your agent can tell you what your policy actually says.
If you bought a home and later learned it had been a lab, the issue may be less about your homeowners policy and more about the sale. Some states place disclosure duties on sellers. According to the Minnesota Revisor of Statutes in 2024, Minnesota requires sellers who know of meth production on a property to disclose it in writing before a sale. Buyers there may sue for cleanup costs within six years. A real estate attorney in your state can tell you what the seller owed you and how long you have to act.
Records your insurer will need
Meth claims lean on documents more than most, because the contamination cannot be seen. The adjuster will want proof that residue exists and where it is. The adjuster will also want to know how much of it is above whatever standard applies at your address.
Useful records usually include the following.
- Any law enforcement report, property notice or health department order tied to the address.
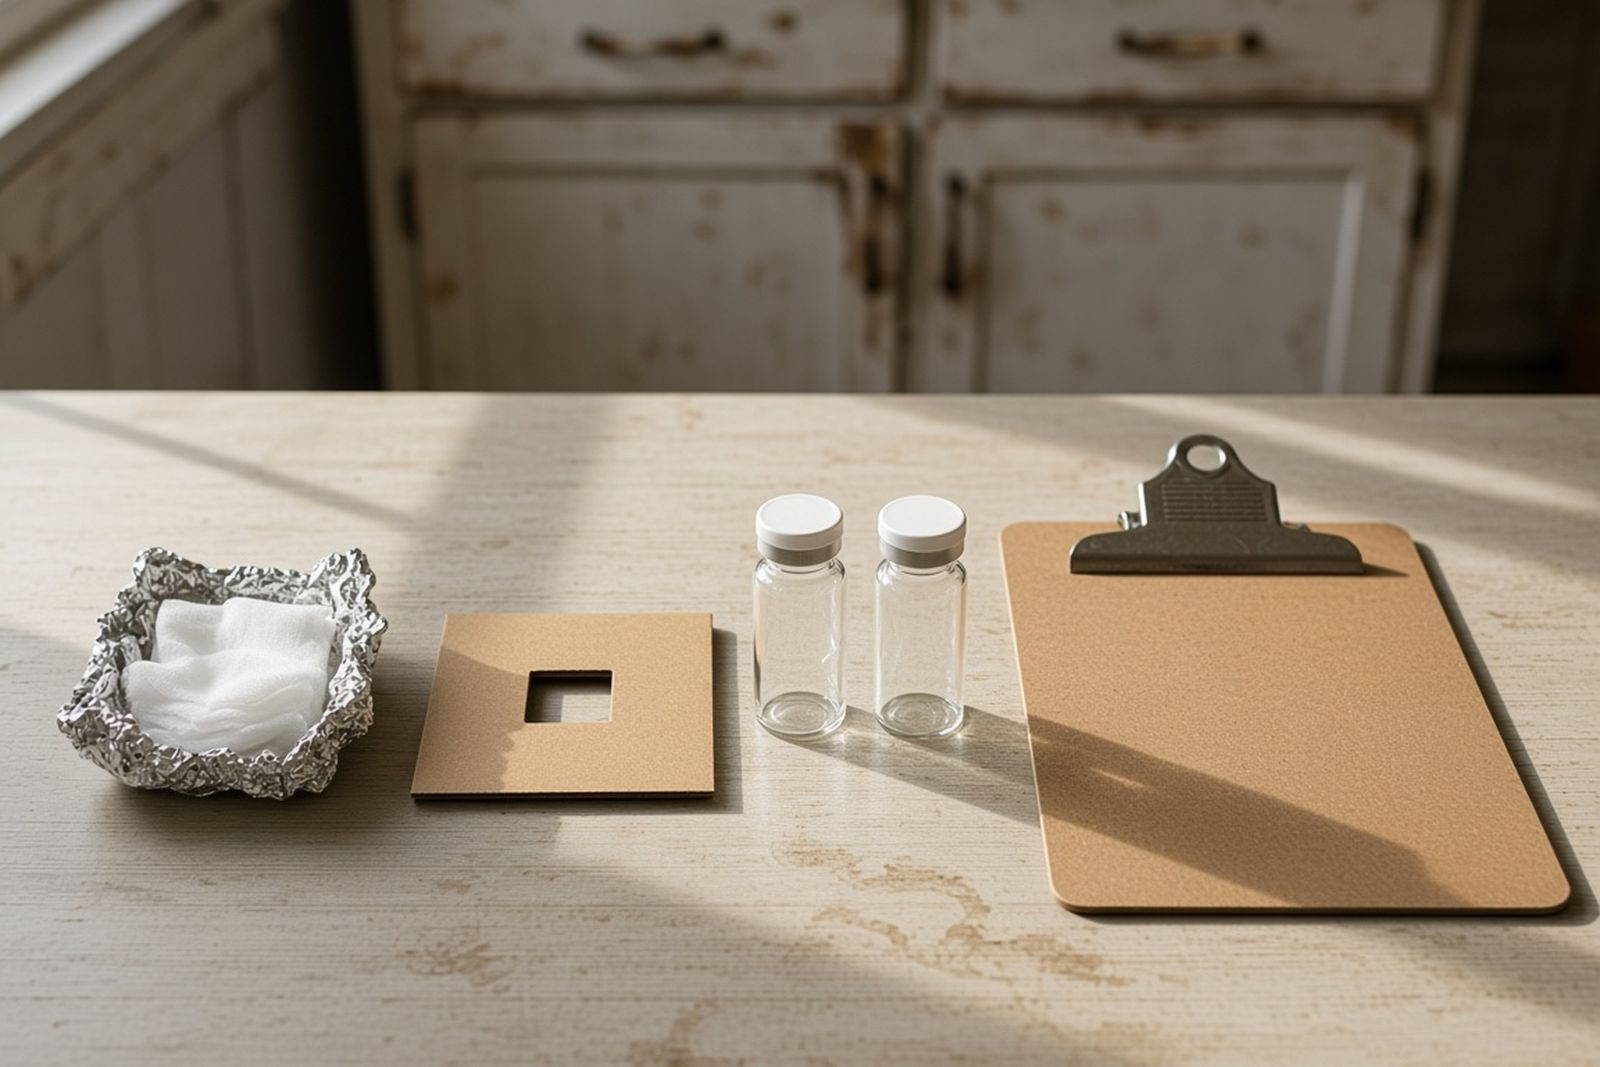
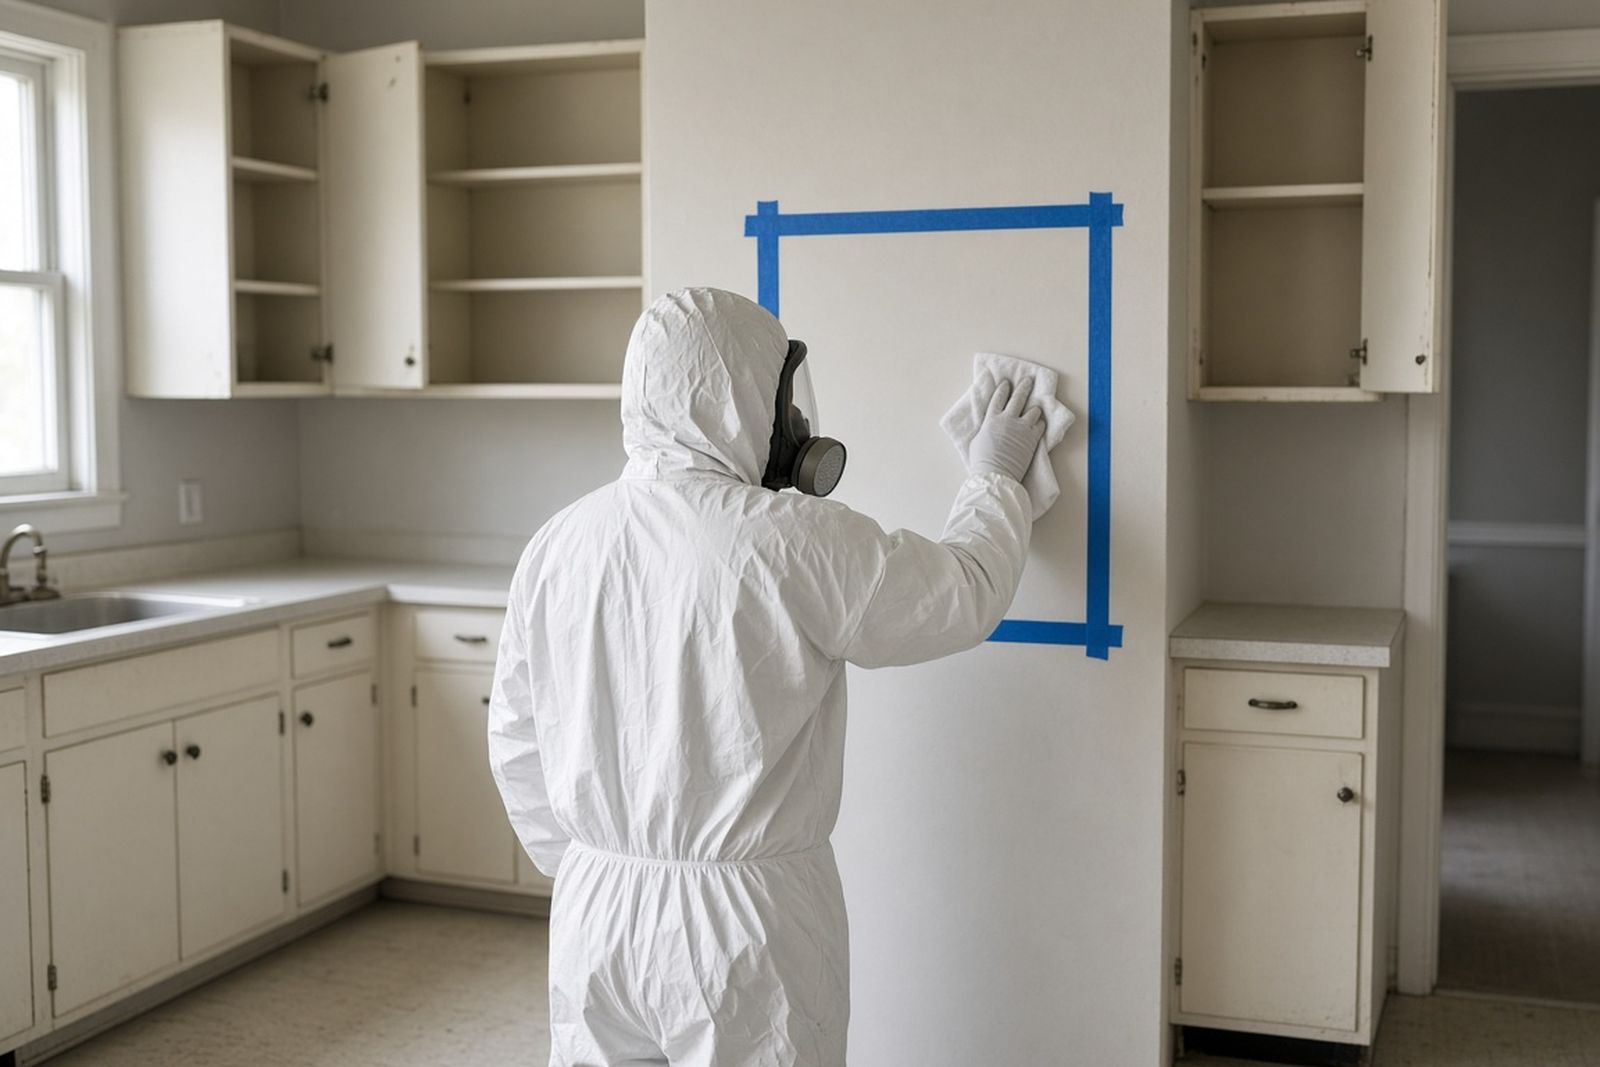
- First wipe sample results from an accredited lab, with a map of where each sample was taken.
- Chain-of-custody forms showing who collected and handled each sample.
- The written cleanup work plan that separates cleaning, removal, and heating and cooling (HVAC) work.
- Clearance results from after the cleanup showing the property met the standard that applies.
- Lease records, move-out dates and inspection notes if the property was rented.
How do test results affect your claim?
Numbers from an accredited lab give everyone something solid to discuss. Without them, the adjuster is weighing one suspicion against another.
The standard those numbers are compared against depends on where your property is. States that set a number limit for surfaces do not all use the same one. Some have no limit at all. A result that calls for full cleanup in one state may call for less in another. So the adjuster needs to know which standard applies at your address.
Where the samples are taken matters as much as the result
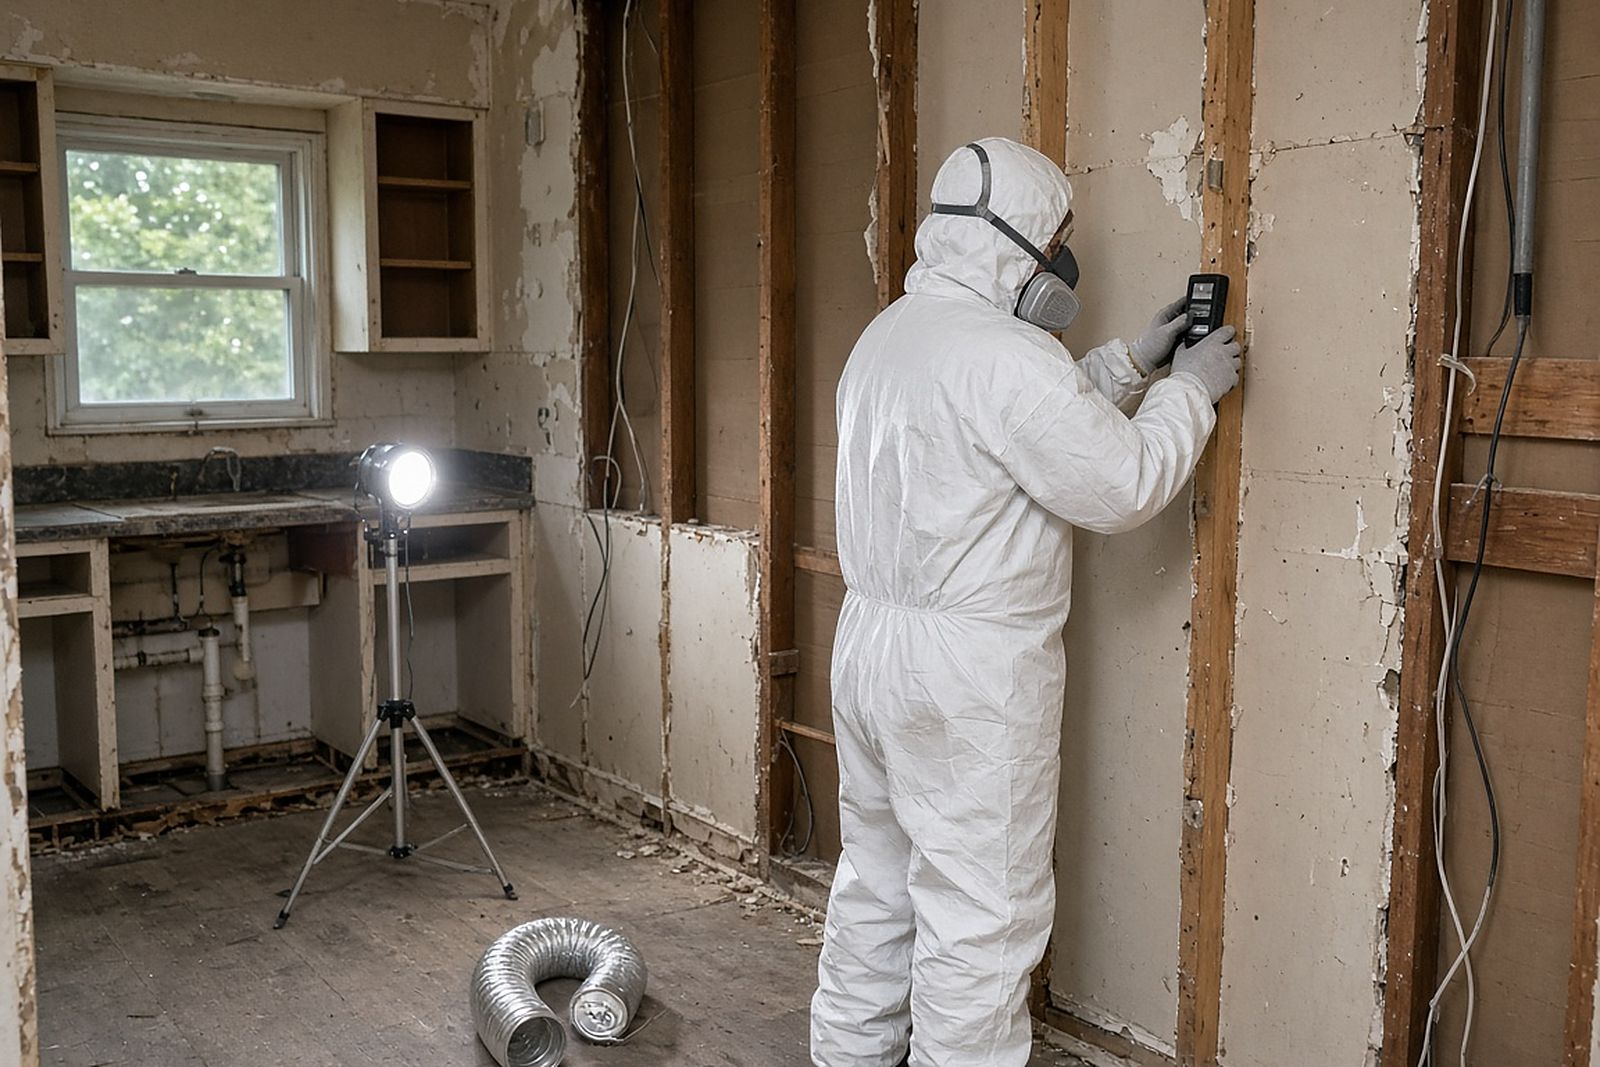
How the sampling is planned matters as much as the result. Wipes taken from a single room tell the adjuster little about the rest of the house. A good sampler explains why each spot was chosen, such as the kitchen, the bedroom with stained ceilings and a return air grille. That helps the insurer see how far the problem reaches and which rooms may need no more than cleaning.
Composite samples combine wipes from several spots into one lab test. They can lower lab cost but make it harder to pinpoint the source. Ask the sampler how the method will affect the insurer's ability to tell heavily contaminated rooms from lightly affected ones.
Ask your sampler to state in the report which standard the results were compared against and why. That one sentence can save you weeks of back-and-forth with an adjuster who does not know the rules at your address.
An example claim: the landlord who found out at move-out
This walk-through blends common situations to show the process. It is not drawn from a real claim. A landlord inspects a single-family rental after the tenants move out. The landlord notices a chemical smell, stained ceilings in one bedroom and taped-over vents. A neighbor mentions that police visited the house months earlier.
The landlord keeps the house vacant and locked, calls the insurance agent and orders first sampling from an independent sampler. Results from several rooms and the return air duct are above the state standard.
The landlord's policy includes a tenant damage endorsement. But it also contains contamination wording. The insurer asks for the lab results, the lease, the move-out inspection and the police report. It then issues a written position that covers part of the removal work and denies the rest.
In this example, the landlord pays the uncovered part and keeps every record for future disclosure. The landlord schedules clearance sampling before listing the unit again. A real insurer could decide differently in either direction. The point is that sampling and records made a decision possible at all.
What does cleanup cost, and why does it matter for the claim?
Insurers compare the estimate against the evidence. So a clear, itemized work plan persuades better than a single total. Price depends on the size of your property and how far the residue spread. It also depends on which materials must be removed instead of washed, plus heating and cooling work, sampling and waste handling.
Any published average is only background. Past figures from single state programs are years old. They reflect local labor, disposal and sampling costs, so they cannot stand in for a quote on your property. The itemized plan for your address is what the adjuster will actually weigh.
Ask the contractor to price assessment, cleanup and clearance testing as separate items. If the insurer accepts some items and not others, you will know exactly what is left for you to pay.
Five mistakes that weaken a meth lab claim
Well-meaning owners sometimes make choices that make the claim harder to judge later. Most come from wanting the property back in use quickly, which is easy to understand.
- Painting over walls or replacing carpet before sampling, which can hide evidence and may not lower the residue.
- Letting new tenants or family members move in before clearance results are in.
- Hiring one company to sample, clean and clear without checking whether your area requires independent sampling.
- Throwing items away or cutting out drywall before the adjuster has had a chance to inspect.
- Relying on spoken promises from anyone about what insurance will pay.
What if no insurance applies?
Many owners end up paying for some or all of the work themselves. That is frustrating. But it does not mean you can skip the cleanup or cut corners, especially if you plan to rent or sell the property.
Legal requirements also differ widely. The Legislative Analysis and Public Policy Association reported in 2025 that, as of April 2025, 18 states plus D.C. had no laws at all governing cleanup of properties contaminated by controlled substances. Where no law applies, your county health department can still help you choose a cleanup standard you can defend.
Other ways to recover costs
You may also have options outside insurance. These include a security deposit, a claim against a former tenant, or a claim against a seller who failed to disclose known history. An attorney can tell you which are realistic where you live.
If the property is your home and you have been living in it without knowing its history, talk with your doctor about any symptoms that worry you. This matters most for young children. The cleanup and the claim can wait a day while you look after your household's health.
The order of steps
Keep the property empty. Call your agent to report the situation and ask for a copy of the full policy with all endorsements. Arrange first sampling that fits your state's rules.
Share the results with the insurer and ask for a written coverage position. Only then approve large-scale removal. Keep clearance reports with the property records for good. Future buyers, lenders and tenants may ask for them years from now.
Last, write a short timeline while the details are fresh. Note when you learned of the history, who you called, when samples were taken and when each decision arrived. Adjusters, attorneys and future buyers all find a dated summary easier to trust than memory.