Short answer
Usually not. Homeowners policies generally exclude motor vehicles, so cleanup inside your car, truck or van is normally reviewed under an auto policy. Comprehensive or collision coverage may apply, depending on what happened. Your insurer may also decide the vehicle is a total loss and not pay for cleanup. Call your auto insurer first and get its answer in writing.
Why your homeowners policy is probably the wrong place to start
Most homeowners policies leave out motor vehicles almost entirely. The car in your garage is treated as its own risk. It is insured under a separate auto policy with its own coverages and deductibles.
That surprises many families, especially when something happened in the driveway or garage. The place feels like part of your home, but the damaged property is the vehicle. A homeowners adjuster may look at a stained garage floor. The seats, carpet and roof lining go to the auto insurer.
There are a few narrow exceptions. Some homeowners policies give limited coverage to certain unregistered vehicles, golf carts or equipment used on the property. An RV, camper or boat may have a policy all its own. Read the summary pages of your policies side by side. Then ask each insurer directly which one handles the question.
Which auto coverages might apply?
Auto policies usually split damage to your own car into two parts. Collision covers damage from hitting another vehicle or an object. Comprehensive is sometimes called other-than-collision. It covers many events that are not crashes, such as theft, vandalism, fire and certain animal damage.
A body-fluid incident after a crash may be reviewed along with the collision claim. An incident in a parked car is more often looked at under comprehensive. Examples are an unattended death, a break-in or vandalism. Whether either one applies depends on your policy wording and its exclusions. It also depends on whether you bought that coverage at all. Liability-only policies generally do not pay for your own vehicle.
- Collision: may be considered when the mess follows a crash you are already claiming for
- Comprehensive: may be considered for non-crash events like vandalism, theft or a death in a parked vehicle
- Rental reimbursement: may help pay for getting around while your vehicle is out of service, if you carry it
- Liability only: typically covers damage you cause to others, not cleanup inside your own car
Why an insurer may total the vehicle instead
Every claim for damage to a car is weighed against the car's actual cash value. That is what the car was worth just before the damage. If the cleanup, parts and labor cost close to that value, your insurer may decide it is cheaper to settle the car as a total loss. The cutoff differs by insurer and by state.
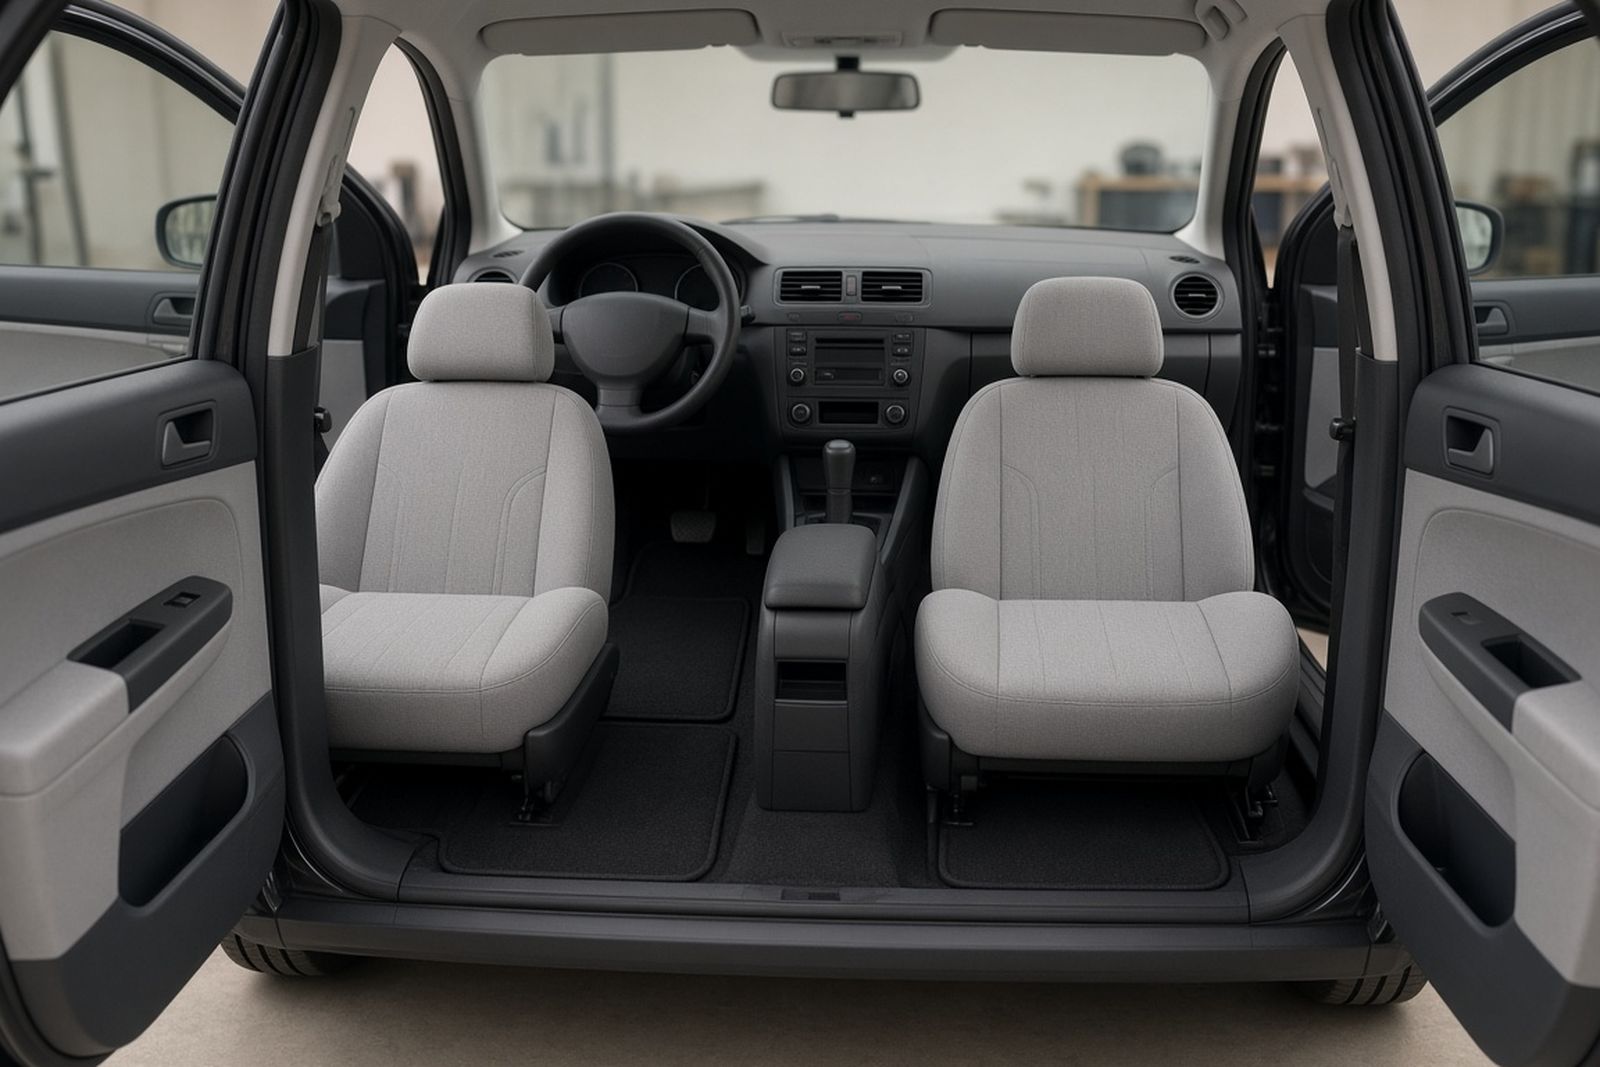
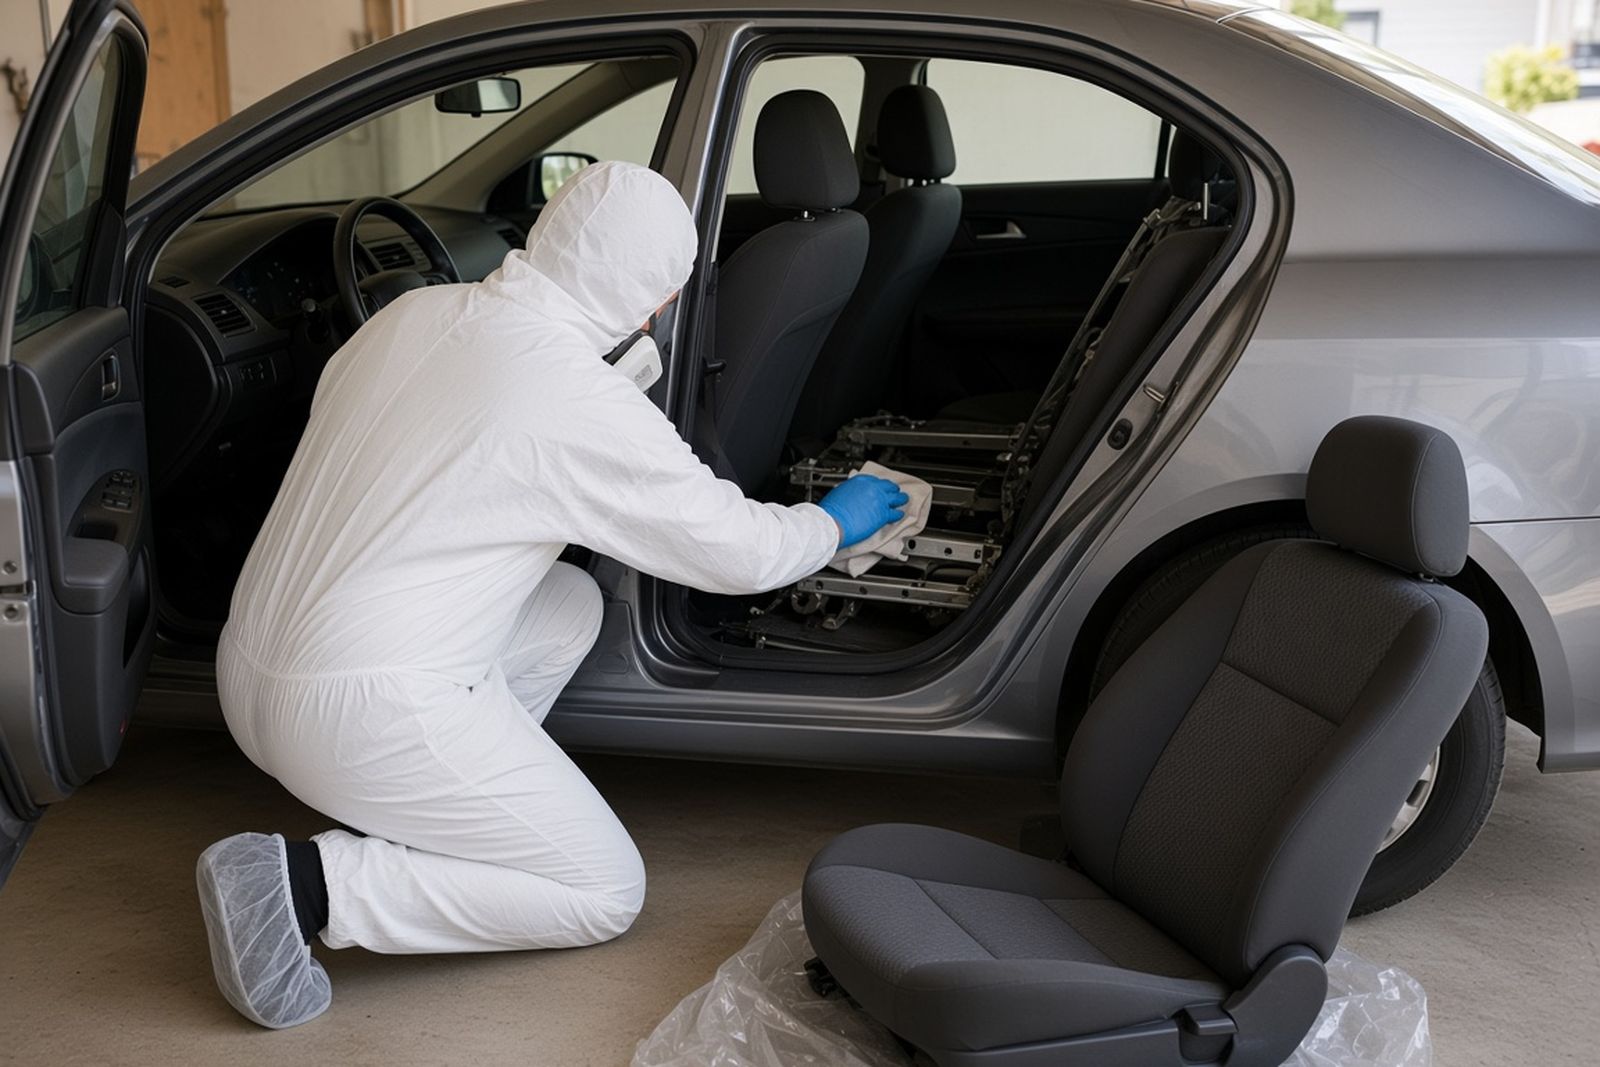
Cabin cleanup can cost a lot next to the value of an older car. Soiled foam, carpet and padding need to come out. Sometimes the roof lining or parts of the heating and cooling system do too. A ten-year-old sedan may not justify that work on paper, even if it runs perfectly.
A total-loss decision is not always bad news. It can spare you from living with a car tied to painful memories. If you want to keep the car anyway, ask whether you can keep it and have its salvage value taken off your payment. Ask what title brand your state would apply. Title rules vary by state and county; verify with the local authority, usually the motor vehicle agency.
How a claim unfolds: an illustrative case
Here is a made-up example to show how this works; Marcus is not a real client. Marcus is a rideshare driver. Late one night he picks up a rider who becomes ill and bleeds from a head injury after a fall at the curb. An ambulance takes the rider away. Blood has soaked into the rear bench and pooled in the seat track. It has also stained the carpet behind the driver's seat.
Marcus stops driving at once. He does not try to shampoo the seat, since that could push fluid deeper into the foam. He takes photos of the rear cabin and notes the trip details in the app. Then he calls two parties: his own auto insurer and the rideshare platform. The platform may have its own cleaning-fee process. His personal policy may treat driving for pay differently from personal driving.
A vehicle biohazard technician inspects the car and writes a work plan with separate lines. One is removal of the rear seat foam. One is new carpet and pad. One is disinfecting the metal floor and seat rails. The last is cleaning the rear air vent. Marcus sends that plan to each party. He asks, in writing, which items each one will review. He does not assume anything is covered until he has those answers.
Does it matter who was in the car or how they were hurt?
It can. After a death or serious injury, the car may be held for a time. Police, a medical examiner or a coroner may need to release it before any cleanup begins. Do not start the cleanup, or let anyone else start, until you know for sure that the car has been released.
If the incident involved a suicide, your insurer will usually treat it like any other covered event under the part of the policy that applies. You do not have to explain more than the adjuster needs to process the claim. If you or someone close to you is struggling, you can call or text 988 to reach the 988 Suicide and Crisis Lifeline at any hour.
Work and fleet vehicles add another layer. A delivery van, ambulance or company truck is usually insured under a business auto policy. If an employee was hurt, the employer's workers compensation insurer may be involved. If you manage a fleet, send the claim through whoever handles your company's insurance. Do not file on your own.
Documentation that helps an auto adjuster
Your adjuster needs to see how far the fluid went, not just the stain on the surface. Take photos before anything is touched, unless there is an urgent safety reason to move the vehicle.
Keep the car closed and parked out of direct sun if you can. Heat speeds up odor and can make the cabin harder to assess.
While you wait, do not sit in the affected seat or run the fan on high. Moving air can carry odor and fine residue into vents and fabrics that were clean before. That adds to the work and the bill.
If the vehicle has to be towed, tell the tow operator what happened before the truck comes. The driver may want to wear gloves, cover the seats they touch or send a different truck. A note on the tow ticket also becomes one more piece of your claim record.
- Outside photos that show the plate, the VIN sticker and the overall condition
- Inside photos from each open door, then close-ups of every affected seat, belt and panel
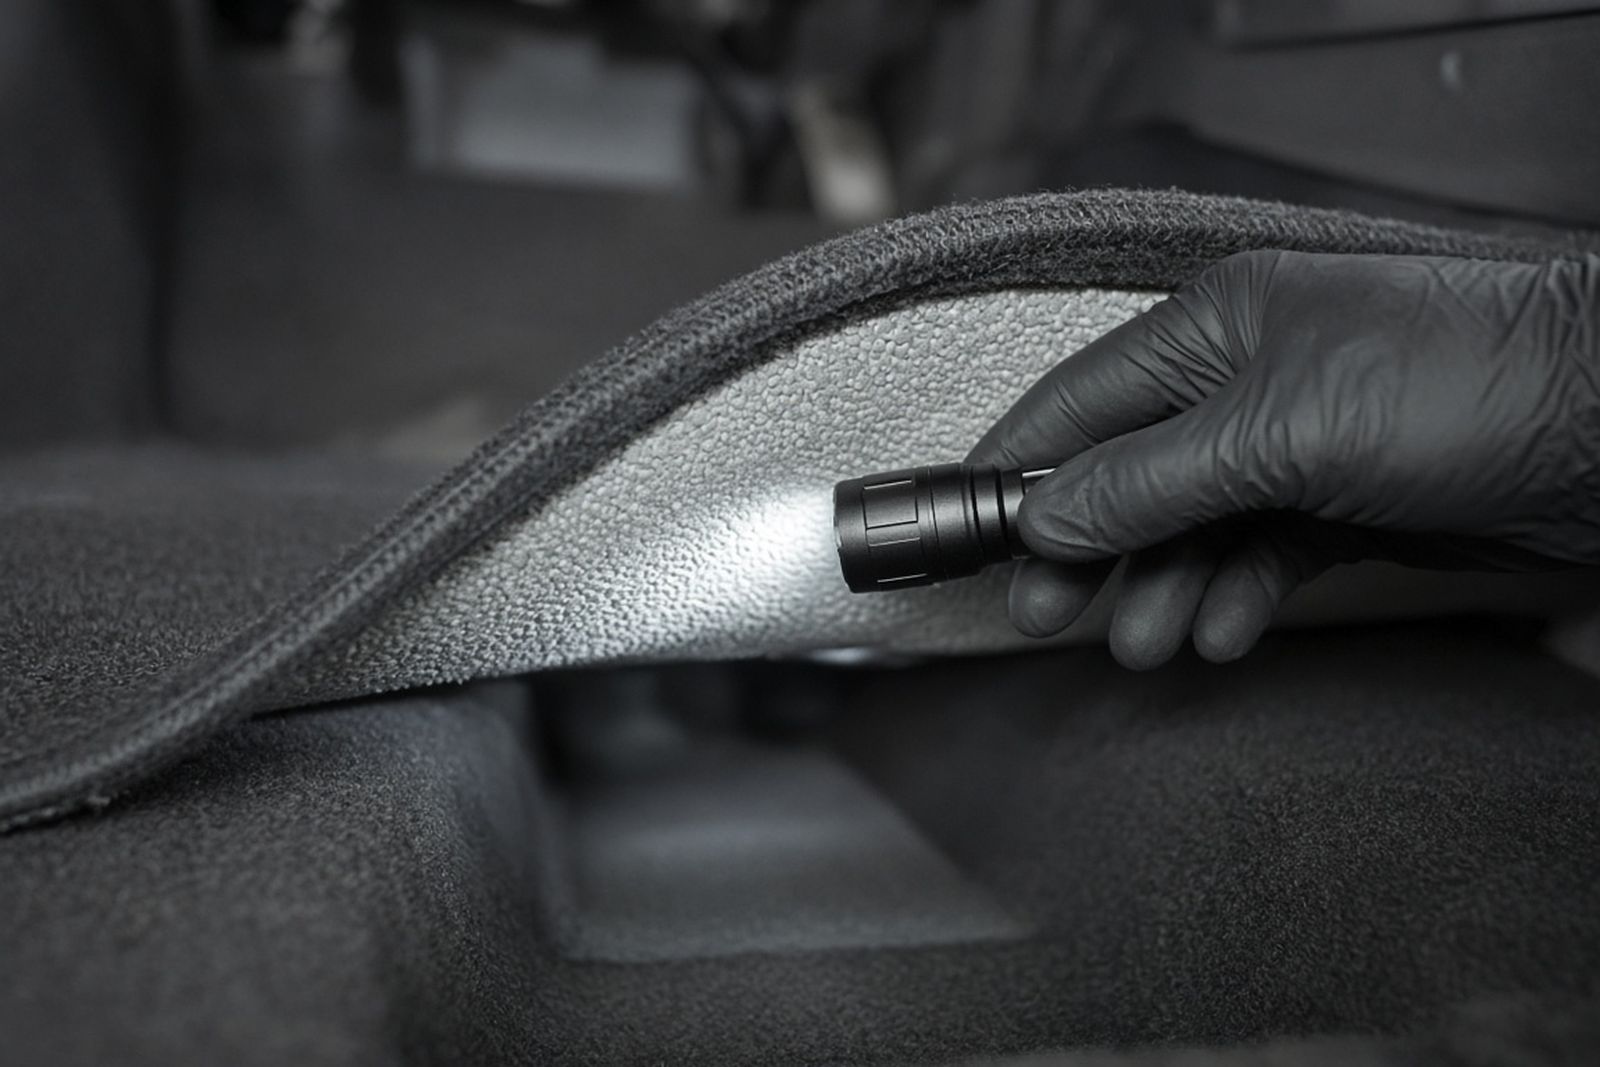
- Photos under the seats and along the seat tracks, where fluid often collects unseen
- The police report, incident number or medical examiner case number, if one exists
- The cleanup company's written work plan, listing each part to clean or replace
- Any receipts for towing, storage or a rental vehicle
Detailing instead of a claim
You can skip the claim and have the car detailed, but think about what detailing really does. A detail makes the inside look and smell clean. It does not reach the middle of the foam, the back of the carpet or the metal floor. It also does not include a legal way to dispose of soaked materials as regulated waste.
Some germs can still infect people from a surface long after a spill dries. That is one reason a proper cleanup removes soft, absorbent materials that no one can prove are clean. It does not just cover them with scent.
Skipping the claim may still make sense for a small, contained incident on a hard surface. Ask a cleanup company for an honest opinion before you decide. Ask whether the job is so small that filing would cost you more in deductible and premium than it pays back.
Questions for the auto carrier before work begins
Call your auto insurer and take notes. Then follow up by email with a summary of what you were told. Crashes are common, so insurers handle vehicle claims every day. NHTSA reports that police reported an estimated 6.18 million traffic crashes in the United States in 2024. Biohazard cleanup inside a cabin is less common. Your adjuster may need your help to understand the work involved.
- Which part of my coverage are you reviewing: collision, comprehensive or something else?
- Will you inspect the vehicle before any seats, carpet or trim are removed?
- Is there a cost level at which you would call the vehicle a total loss?
- Do you pay the cleanup company directly, or pay me back?
- Does my rental reimbursement coverage apply while the vehicle is out of service?
- If the vehicle is totaled, can I keep it, and how much would you take off for salvage?
If the carrier says no
Ask for the denial in writing, with the exact policy wording it relies on. Sometimes a denial is not a true exclusion. It may come from a missing document or an incomplete work plan. A clearer estimate can change the outcome.
If you still disagree, ask about a second inspection or an appraisal. You can also ask about the complaint process at your state insurance department. If you decide to pay on your own, get at least two written work plans. Compare what each one removes and what it only cleans. Ask how the company will confirm the cabin is ready for the next person to sit in it.