Short answer
It depends on your policy and on how your insurer labels the event. Some insurers review tear gas damage under vandalism, civil authority or other parts of the policy. Others point to exclusions for government action or pollutants. You may also be able to file a separate claim against the city or agency. Report the damage fast, keep a record of the residue and ask for every coverage decision in writing.
Why tear gas damage is hard to label
Tear gas usually gets into a home through police action. It may be a standoff, a warrant being served or a protest that spills into your street. The damage is real. But it does not look like a normal homeowners claim.
Residue from CS tear gas or OC pepper spray coats surfaces and soaks into fabrics. It gets pulled into your heating and cooling system. You may have broken windows or doors from the police action itself. Often an irritant hangs on that makes the house hard to be in, or not fit to live in at all.
Insurers look at the cause first. Your policy may treat the event as damage caused by others, as a government action or as the release of an irritant chemical. Each reading points to different wording in your policy. Two insurers can reach different answers on the very same facts.
You do not have to argue about the label on the first call. Your job is to report the event clearly and describe what was damaged. Then ask the adjuster, the person who handles your claim, which parts of the policy are under review.
The parts of the loss an insurer may review
It helps to break your damage into separate pieces. Insurers often decide each piece on its own, so it is common to get a yes on some parts and a no on others.
- Damage to the building, such as broken windows, doors, drywall or ceilings from canisters or forced entry.
- Residue on hard surfaces, such as floors, cabinets, counters and walls.
- Soft items that soaked up the agent, including mattresses, padded furniture, curtains, clothing and carpet.
- Parts of your heating and cooling system, including filters, return vents, the blower and the ducts a crew can reach.
- Additional living expenses, which are your extra costs if you cannot stay in the home while it is cleaned.
- Food, medicines and personal care items that may have been exposed.
What about going to the city or the police agency instead?
When a government agency caused the damage, some owners file a claim against that agency. They do this along with their own insurance claim, or in place of it. Many places require a written notice of claim within a set time, and the deadlines can be short. Rules vary by state and county, so check with your local authority. Think about speaking with an attorney early.
Results from these claims vary widely. Westword reported in 2019 that after a 2015 SWAT standoff in Greenwood Village, Colorado, the city offered only $5,000 toward an innocent family's insurance deductible, and courts denied further payment. Police had used tear gas and explosives on the home. That is one case, not a rule. But it shows why you should not count on the agency to cover your whole loss.
If you file with both your insurer and the agency, tell each one about the other. Your insurer may have the right to go after the agency once it has paid you. Being open with both sides now prevents confusion later.
Why the type of agent matters to your claim
CS and OC act differently inside a building. That changes the cleaning plan and the cost. CS tends to settle as a fine powder. Foot traffic, damp air and airflow can stir it back up. OC leaves an oily film that clings to fabrics and surfaces.
The chemistry matters too. The products that break down CS powder are not the ones that lift OC oil. A cleanup company that understands this can explain why it chose each product. That makes the invoice easier for an adjuster to accept.
If you can, ask the agency that responded which agent it used and how many canisters went off inside. Put the answer in your claim notes. If you get no answer, note that too.
When the residue came from next door
You do not have to be the target to have a claim. In a duplex, townhouse or apartment building, CS canisters may be fired into one unit. The gas can then drift through a shared attic, gaps in the walls and connected ducts into your home.
If this is you, you may notice the problem only after you come back. Your eyes and throat burn whenever the furnace runs. The steps are the same as for the unit that was targeted. Photograph the rooms, keep the doors closed, leave the system off and call your insurer.
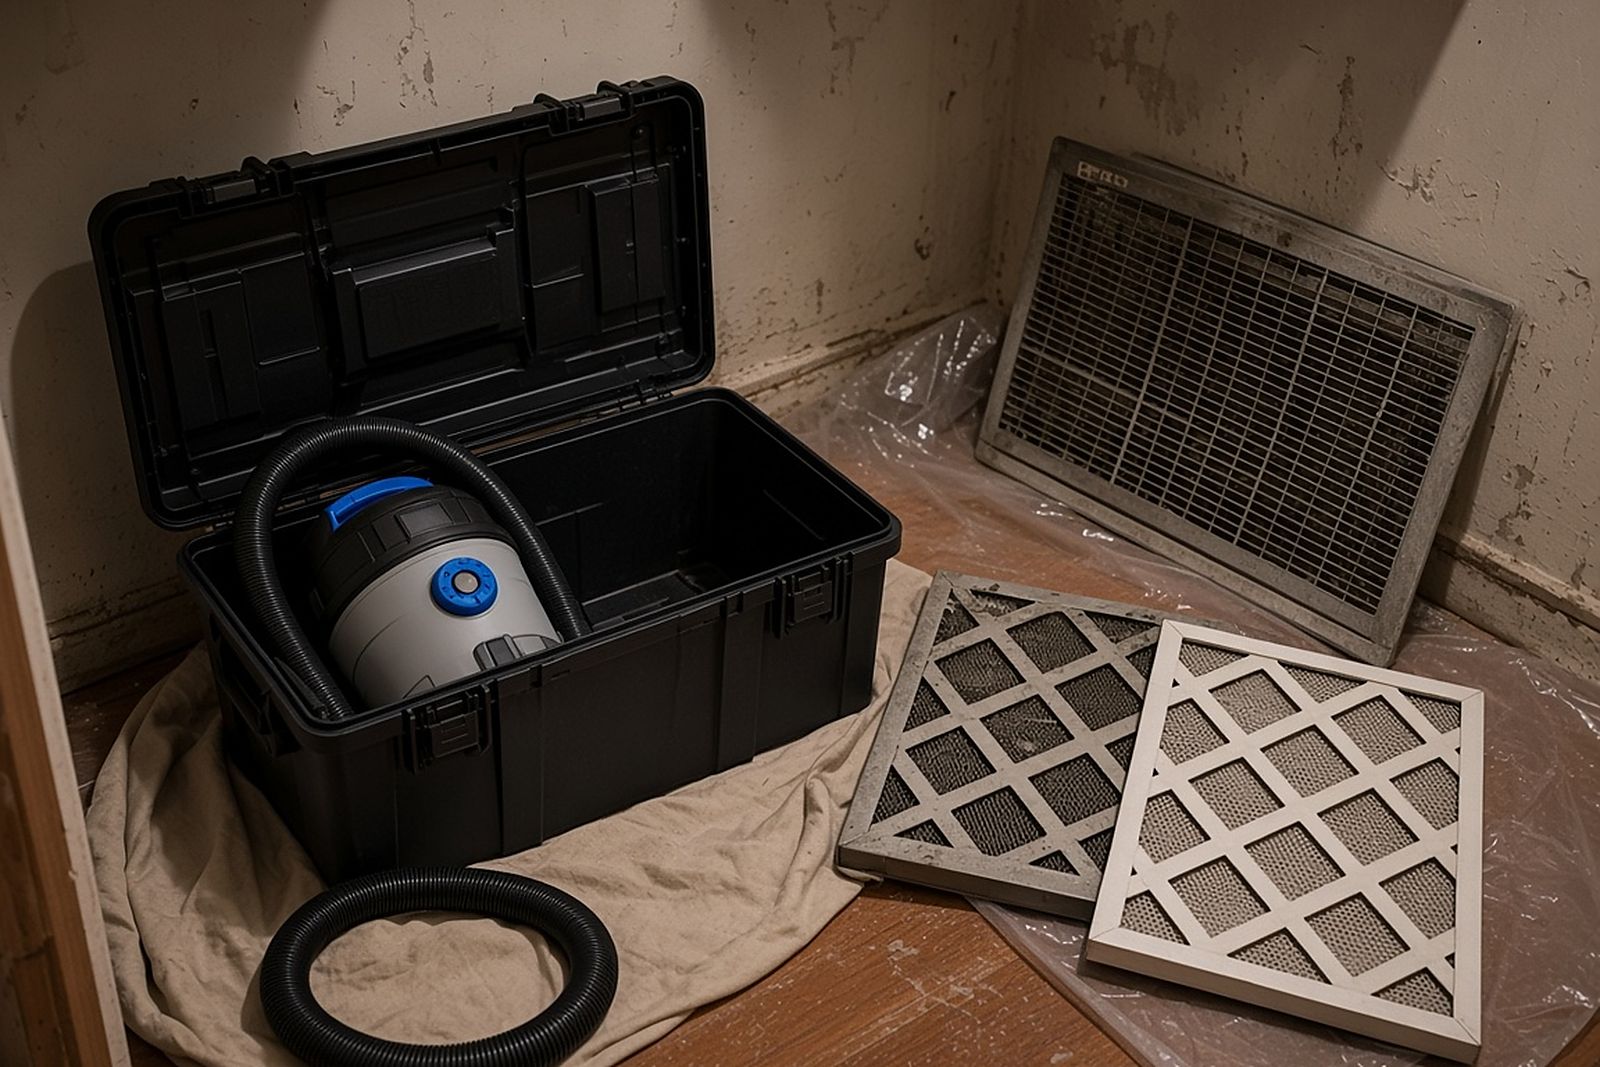
A tear gas cleanup company should inspect both your living space and your heating and cooling system. Several things belong in your claim file. One is proof of residue in the return air box of the system. Another is a note on any crib mattress or padded pieces that must be replaced. The last is a report listing each item removed, the products used and the areas treated.
Insurers sometimes accept additional living expenses and part of the cleaning but question the work on the air system. Photos of a loaded filter and of residue inside the return air box are the kind of proof that can lead an adjuster to take a second look. No outcome is guaranteed for any claim.
Records that make a tear gas claim stronger
Residue is often hard to see in photos. So your records need to capture two things: the damage you can see and the signs that the irritant is still there.
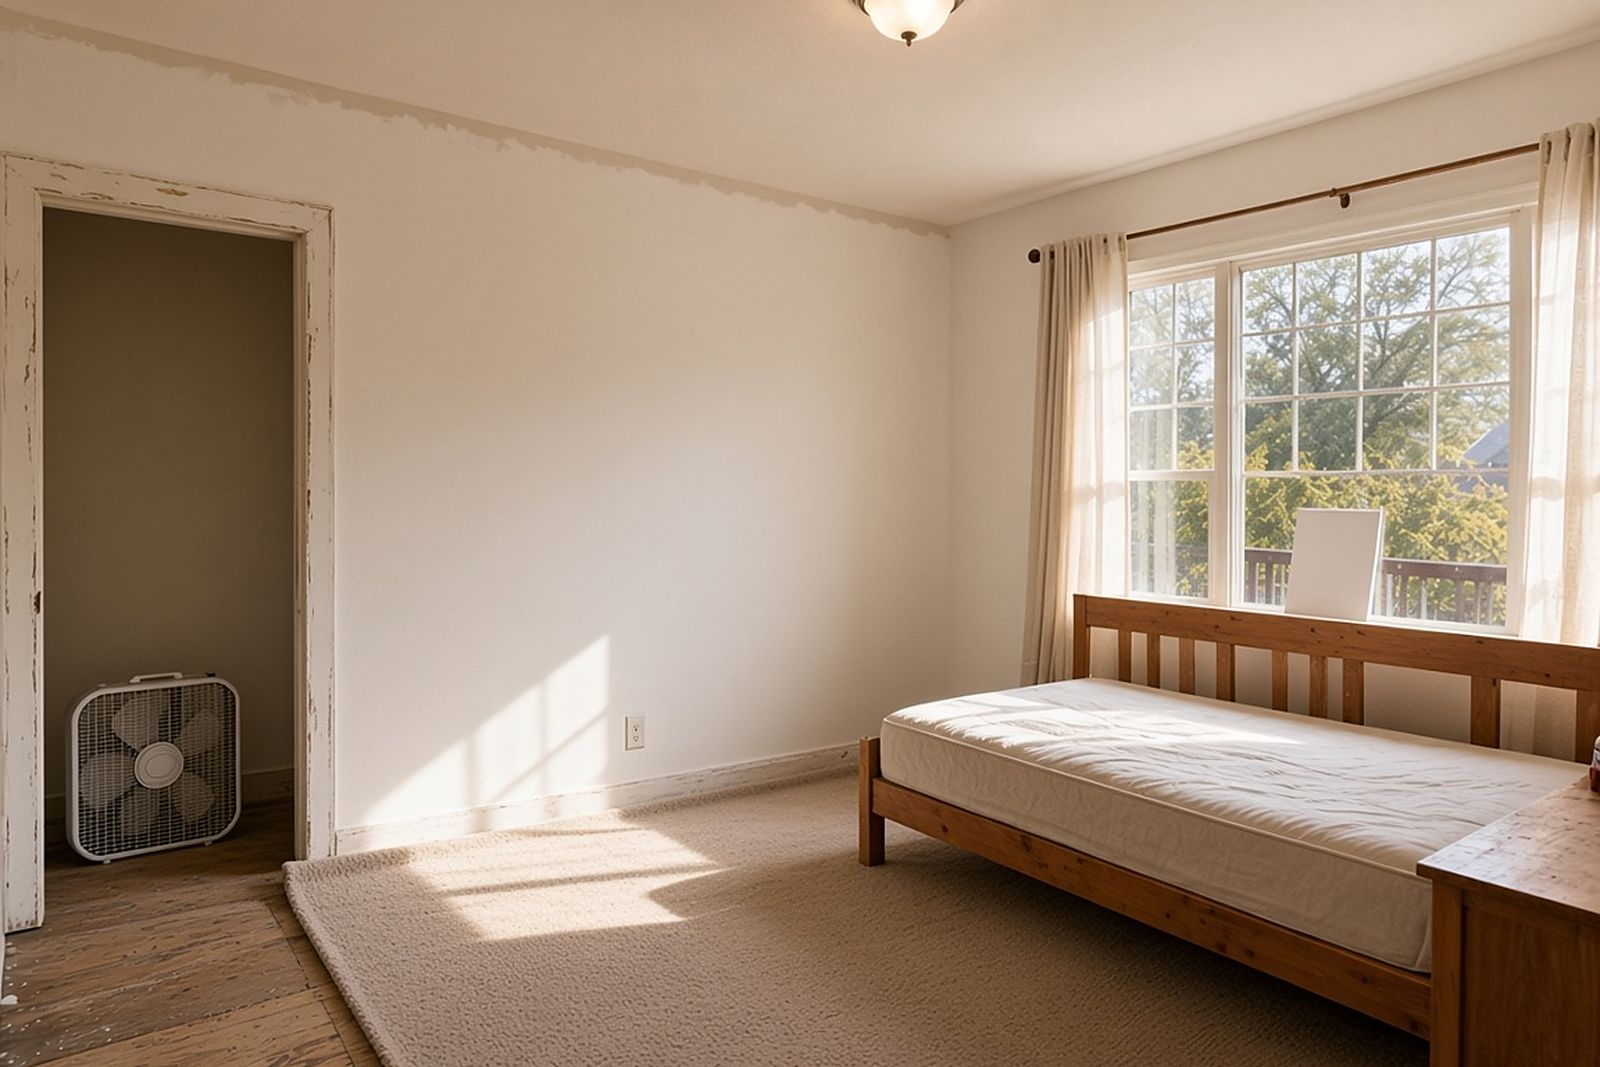
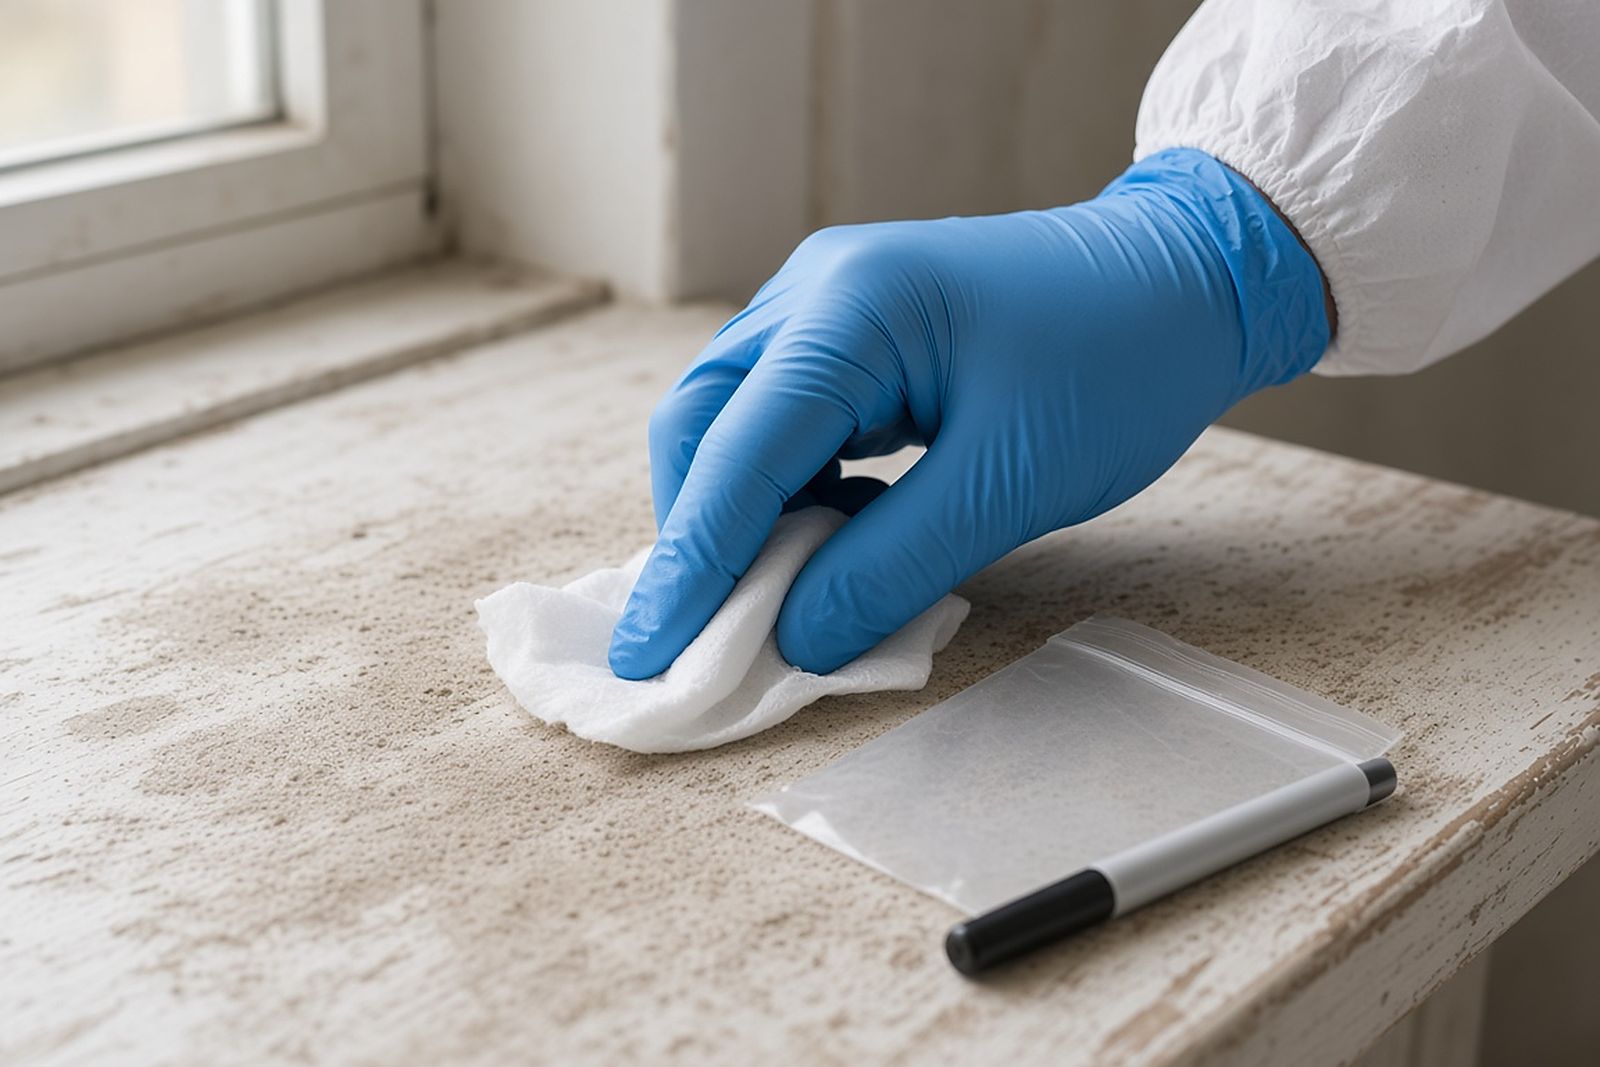
Start with wide shots of each room. Add close-ups of where canisters hit, powder on window sills and surfaces, and any broken fixtures. Keep a written log of the symptoms people felt when they went back in, with dates and rooms. That log is not a medical record. But it shows the adjuster why you could not use the house.
Ask your cleanup company to record which items it cleaned, which it advised you to throw out and why. Photos of the filter before and after it is replaced are useful. So are notes on which ducts were inspected.
Keep your receipts for hotel stays, meals and replacement clothing. If a doctor treated anyone in your home for exposure, keep those records private. Have them ready in case your insurer or the agency asks for them.
Five things to avoid before the adjuster visits
It is natural to want your house back to normal. But some quick fixes cause problems for your claim and for your health.
- Running the heating and cooling system to air things out. That can spread residue into the ducts and other rooms.
- Washing exposed clothing with your household laundry. That can pass residue to other items and to the machine.
- Throwing out furniture or bedding before you photograph and list it.
- Painting over walls or ceilings without cleaning them first. That can trap residue that wakes up again later.
- Signing a contract that hands over your claim rights without reading it closely.
What if your insurer points to an exclusion?
Ask for the denial in writing, with the exact policy wording the insurer relied on. Read it next to your full policy, including any endorsements, which are add-on pages that change the policy. Note any facts the adjuster may have gotten wrong. One example is whether your household had any link to the police action.
If you still disagree, your state insurance department can explain how to file a complaint. An attorney or a public adjuster may also be able to help. That is even more true if you have an agency claim going at the same time. Watch every deadline closely. The notice period for a claim against a government can run on its own clock, apart from your insurance timeline.
Partial approvals and misunderstandings
Sometimes a denial comes from a wrong idea about the residue, not from the policy. An adjuster who has never handled a chemical irritant claim may assume you can just air the house out. A short written note from your cleanup company can change how your file is read. It should say where residue was found and why it keeps coming back to life.
Give a partial approval the same care as a denial. Your insurer may pay to clean hard surfaces but not to deal with soft items or ducts. Ask what more proof it would need to look at those items again. Ask whether it would accept an independent assessment.
First steps for this week
Keep people and pets out of your home until it is safe to be there. Report the event to your insurer and ask which parts of the policy it is reviewing. Ask the agency for an incident or report number and find out its claim deadline.
Then set up a residue inspection that covers both your living space and your heating and cooling system. Keep every receipt. Ask for a written decision on each part of your claim.
If you rent, tell your landlord in writing on the same day you call your own renters insurer. The landlord's policy generally covers the building and its systems. Yours covers your belongings and maybe your temporary housing. Lining the two up early keeps the two insurers from waiting on each other.
Last, look after yourself and your household. Being on the receiving end of police tear gas is frightening, even if you were only a bystander. Talk with a doctor about symptoms that hang on, or with a counselor about the stress. That is a normal part of getting better, not a sign of weakness.